
Employer benefits
Managing retirement investments and company stock concentration
October 22, 2026
By Jamie Hargrave, Cadence Capital Investments
Managing retirement investments and company stock concentration
Employer benefits
Explore Chevron retiree investment management to navigate ESIP concentration risk in San Ramon. Coordinate company stock with your broader retirement plan.
A familiar stock can still create an unfamiliar retirement risk. Chevron retiree investment management starts by viewing the Employee Savings Investment Plan (ESIP), other investments, and retirement income as one picture. For retirees in San Ramon, that means considering how much of their liquid net worth depends on Chevron stock and energy market cycles.
It's understandable to feel attached to company stock after years of work, especially if it has been part of your savings strategy. The goal isn't to react to short-term market moves. It's to understand how much of your retirement depends on one company and whether your overall mix fits your income needs, time horizon, and comfort with risk.
This article explains how to review ESIP holdings alongside other retirement assets, what concentration can mean for your plan, and which factors to weigh before changing company stock holdings.
The structure, stated plainly: investment advisory services at Cadence Capital Investments are offered through Prosperity Financial, a Registered Investment Advisor, which acts in a fiduciary capacity for those advisory services. Securities are offered through Fortune Financial Services, LLC, a Registered Broker/Dealer and member FINRA and SIPC. Insurance and annuity products are offered through licensed affiliates, so the firm is fee-based rather than fee-only: an affiliate may earn commissions on certain products, disclosed before any recommendation. Cadence Capital Investments is not affiliated with, endorsed by, or sponsored by Chevron Corporation.
• Assess Chevron stock alongside your other retirement assets and income sources to understand how much your plan depends on one company.
• Separate investment changes within an account from taking money out, since withdrawals and transfers have different tax consequences.
• Review your plan's available investment choices and fee disclosures before making changes.
• Coordinate retirement investments with your income needs, time horizon, and comfort with risk rather than viewing each account in isolation.
• If your ESIP holds low-basis Chevron stock, evaluate Net Unrealized Appreciation before any rollover.
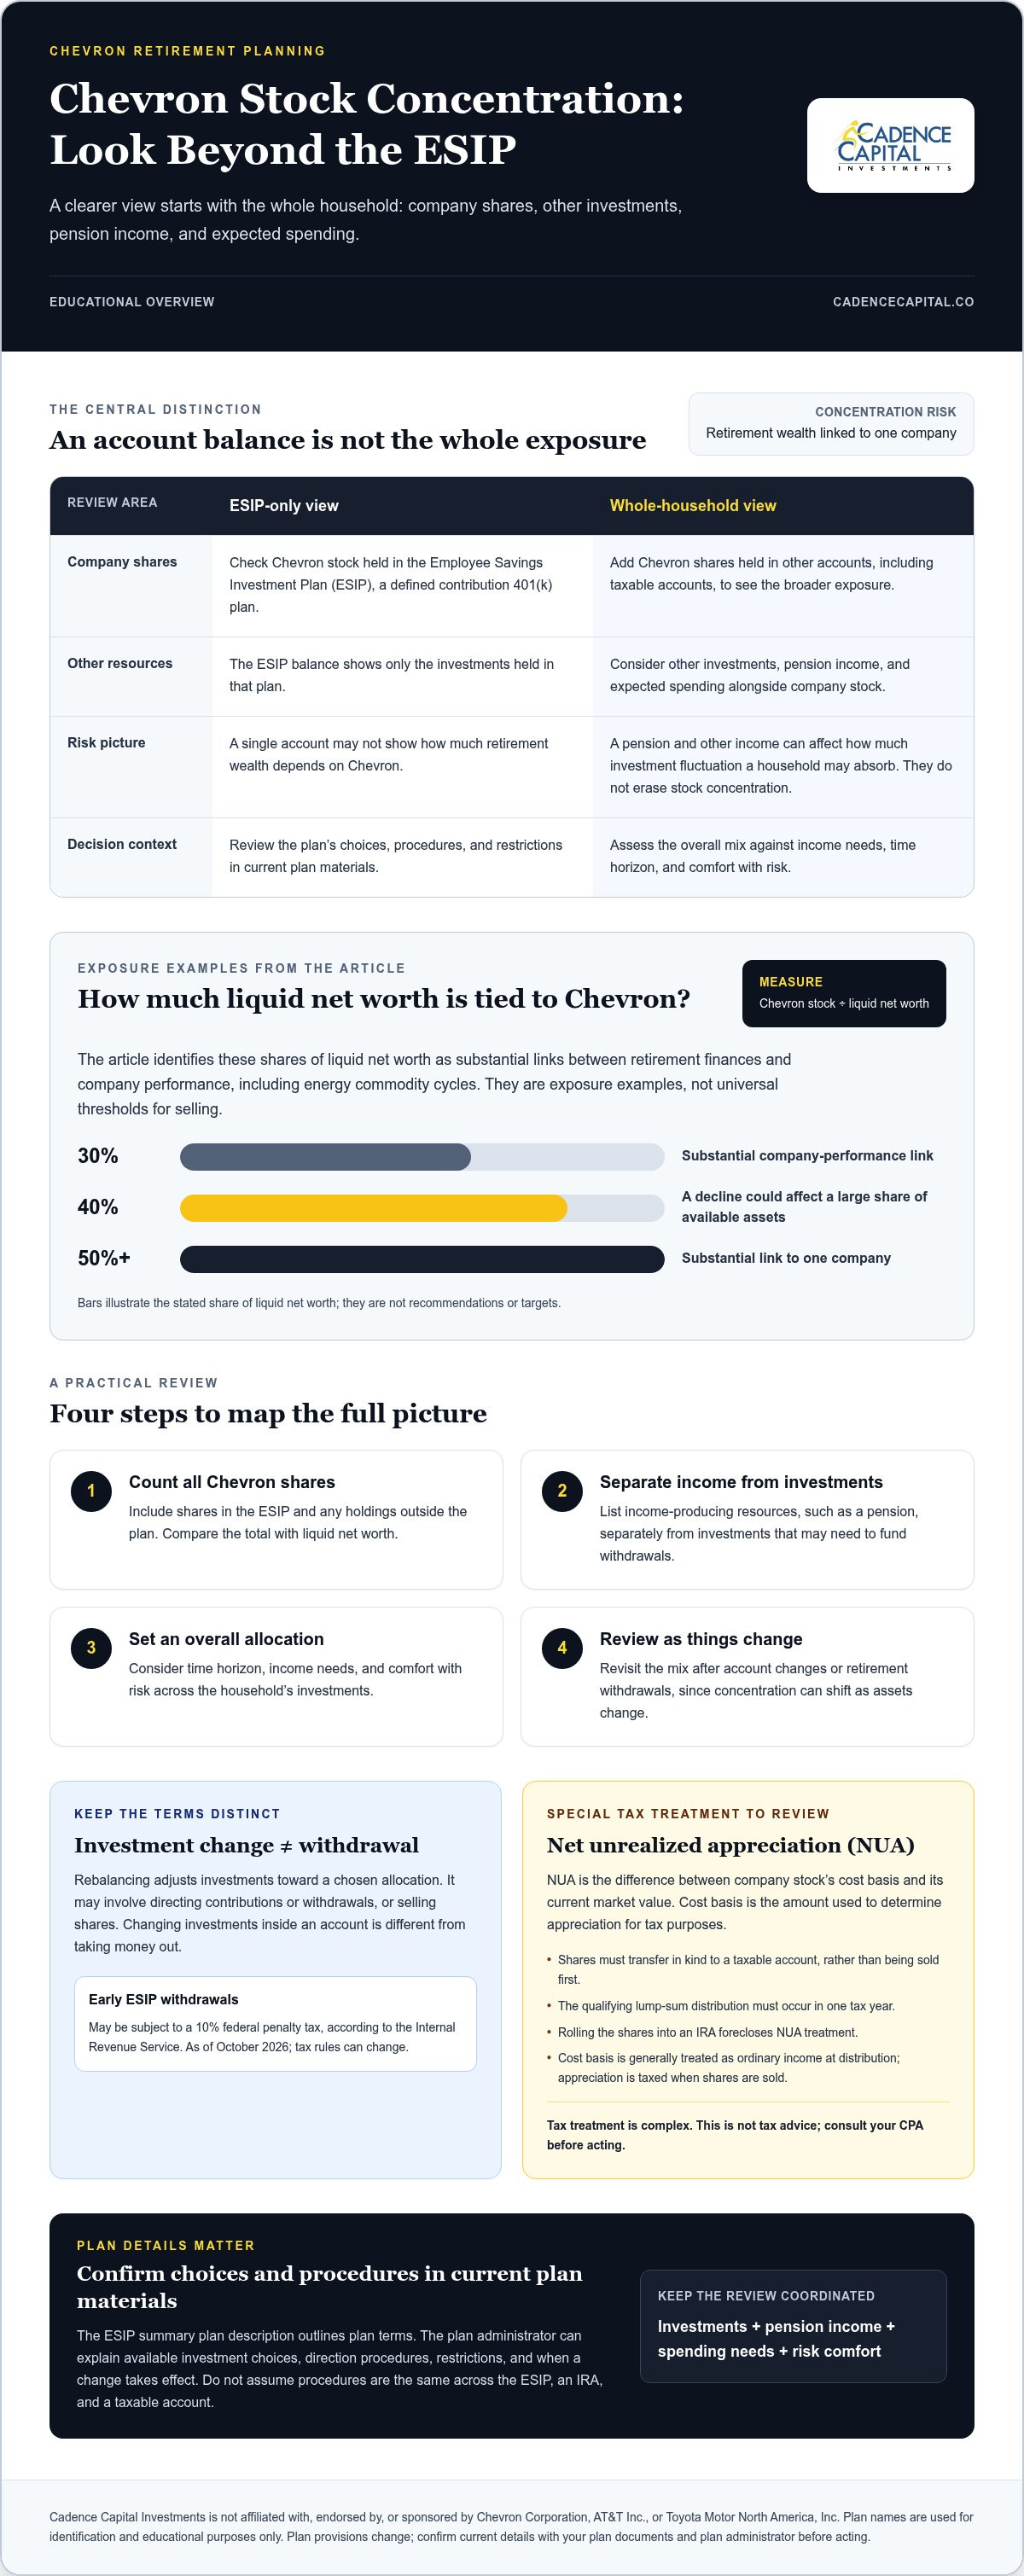
Concentration risk means a large share of your retirement wealth depends on one company. For a Chevron retiree, that can happen when company shares in the ESIP sit alongside stock held in other accounts. The ESIP is a defined contribution 401(k) plan, so its investments are part of your retirement savings, not a full measure of your exposure.
Start with a household inventory, not just the ESIP balance. List Chevron shares in the ESIP and in taxable accounts, then compare them with your other investments, pension income, and expected spending. If Chevron stock represents 30%, 40%, or 50% or more of your liquid net worth, your financial security is closely tied to the company's performance, including energy commodity cycles. These figures describe exposure, not a universal threshold for selling.
If Chevron stock represents 40% of liquid net worth, for example, a decline in that holding could affect a large portion of assets available for retirement needs. A pension and other income sources may affect how much fluctuation your household can absorb. They don't erase the concentration.
A practical review:
• Calculate Chevron stock as a share of liquid net worth, including holdings outside the ESIP.
• Separate income-producing resources, such as a pension, from investments that may need to fund withdrawals.
• Set a deliberate allocation based on time horizon, income needs, and risk tolerance.
• Review the mix after account changes or withdrawals, since concentration shifts as assets change.
Rebalancing means adjusting investments to bring the overall mix closer to a chosen allocation. It can involve directing withdrawals from overweight holdings or selling shares. Selling inside the ESIP doesn't create a current tax bill; selling shares in a taxable account can. Withdrawing money from the ESIP is taxable, and before age 59½ the 10% additional tax may also apply unless an exception does, such as separation from service in or after the year you turn 55.
NUA is the difference between company stock's cost basis inside the plan and its market value. It may be relevant when shares have a low cost basis, but it requires coordinated decisions:
• A qualifying triggering event, such as separation from service, reaching age 59½, disability, or death.
• A lump-sum distribution of the entire plan balance within one calendar year.
• Company stock transferred in kind to a taxable account, not sold first. Rolling the shares into an IRA forecloses NUA treatment.
Taxes. The cost basis is generally taxed as ordinary income at distribution. The NUA is taxed at federal long-term capital gains rates, currently up to 20%, when the shares are sold. The NUA portion itself isn't subject to the 3.8% Net Investment Income Tax, though gains after the distribution can be. California taxes capital gains as ordinary income, so the state-level benefit is smaller than the federal one. Tax rates and rules can change. Consult your CPA before acting.
A personalized strategy weighs the investment plan, pension, other income, and the tax treatment of each possible step.
Retirees may be able to change investments, but options depend on the account and its terms. First identify where each balance is held: the ESIP, an IRA, or a taxable account. Each follows its own procedures and investment choices.
For ESIP assets, review the current summary plan description for available choices, investment direction procedures, and restrictions. The plan administrator can explain how to submit an investment change and when it takes effect.
Asset allocation is how your money is divided among investments. A retiree might compare the ESIP mix with an IRA, taxable investments, and pension income. Company shares held in multiple accounts may create a different overall risk profile than the ESIP balance alone suggests. A written target allocation can help you assess proposed changes against your plan instead of reacting to one price movement.
Before placing a trade:
• List each retirement account and where its balance is held.
• Record current investments, including company shares outside the ESIP.
• Compare the combined allocation with expected expenses and other retirement income.
• Review the account or plan documents for choices and transaction steps.
• Write down the purpose of the change and revisit it at future reviews.
A rollover moves retirement savings from one account or plan to another; an investment change keeps assets in the same account. Before moving ESIP assets, compare investment choices, expenses, services, and features that would change, including age-55 access and NUA eligibility. A rollover can be difficult to reverse.
Review current ESIP fee disclosures and account statements to identify the expenses tied to your holdings. Costs depend on the account, investment choices, and any advisory services used.
Fund expense ratios. An investment's operating cost, expressed as a percentage of assets. Compare it with the fund's objective and risks; a cost comparison is meaningful only when you also compare what each investment is designed to do.
Plan and account charges. These may appear as separate statement lines, while other costs are reflected in an investment's value. Read the ESIP disclosure and statement together.
Transaction charges. These apply to particular activities such as trades, distributions, or transfers. Find the applicable fee language before acting.
Advisory fees. These compensate an adviser for defined planning or investment services. An advisory fee and a fund's expense ratio may both apply; read each disclosure to understand the full arrangement.
For a rollover comparison, review the proposed destination and the option of leaving the balance in the ESIP side by side. A lower visible fee alone doesn't establish that one account is more suitable.
Keep fee analysis separate from other decisions. Long-term incentive awards (performance shares, stock options, restricted stock units) are compensation records, not investment costs. And the Chevron Retirement Plan's lump-sum versus annuity election is a separate, generally irrevocable decision governed by its own election materials.
Chevron's plan documents and administrator explain how the company's retirement plans work, but that's different from personalized planning across a retiree's full financial picture.
Plan education explains features and procedures, such as how an ESIP option works. Investment advice is a recommendation about what a particular person should do with investments. Financial planning coordinates decisions around a household's goals and resources: employer benefits alongside outside investments, a spouse's income, planned expenses, and retirement timing.
To understand what help is available through a Chevron plan, review the current summary plan description and related notices for participant education, investment services, and the administrator's role. If a document uses terms such as "guidance" or "advice," read the surrounding language to learn what service it describes, who provides it, and whether it addresses your personal circumstances.
Before relying on information:
• Ask whether it explains a plan feature or recommends a personal investment action.
• Identify whether it covers only the ESIP or also your other accounts and income.
• Review any written explanation of the service, provider, compensation, and applicable duties.
• Keep the documents and notes you relied on with your retirement records.
Plan provisions and services can change, so current plan documents govern plan-specific details.
Cadence Capital Investments offers financial planning for people coordinating Chevron retirement accounts, pension income, and other investments. Its Chevron employee retirement planning and investment management bring ESIP decisions into the broader retirement picture, while retirement income planning addresses how savings and income sources fit together.
That can be a useful next step when you're weighing company stock concentration, reviewing account expenses, or deciding how investments relate to planned withdrawals. Investment advice isn't tax or legal advice; direct those questions to your CPA or attorney.
All investing involves risk, including possible loss of principal. No strategy assures a profit or protects against loss, and past performance is not indicative of future results.
Many Blackhawk households reach retirement with large employer-plan balances, and for Chevron retirees that often includes a meaningful position in company stock. Retirement planning for Blackhawk residents starts by putting those holdings in context: how much of liquid net worth they represent, what income they need to support, and what the tax tradeoffs of reducing them would be. Cadence Capital Investments provides investment management and planning from its San Ramon office, minutes away in the San Ramon Valley, with phone and video meetings available. Schedule a complimentary conversation with Jamie Hargrave or call (925) 314-8513.
Choices depend on each account's terms. For ESIP assets, review current plan materials for available options and how to direct changes. IRAs and taxable accounts have separate choices and rules. Compare accounts as one household portfolio, considering how each investment supports future spending.
Company-specific exposure, market declines when you need withdrawals, inflation, and liquidity needs. A portfolio concentrated in Chevron shares ties retirement assets to the same employer that may also provide pension and retiree benefits. Investing involves risk, including the possible loss of principal.
There's no universal answer. The decision depends on how much of your liquid net worth the stock represents, your income needs, the cost basis, and the tax treatment of each option, including NUA. Model the choices with your adviser and CPA before acting.

We value your privacy, and we want to help make your experience with Cadence Capital Investments as satisfying and safe as possible. We have established this Privacy Policy to explain how we receive, use, and share information you may provide in connection with your access to this website.
The Site is intended for use only by individuals over the age of 18 who are accessing the Site from inside the United States. By using the Site or submitting any information to us, you acknowledge that you are over the age of 18, are in the United States, and that you consent to our use and sharing of information collected or submitted as described in this Privacy Policy. This Privacy Policy is incorporated into and is subject to the Site's Terms of Use. By using the Site, you expressly consent to the terms of this Privacy Policy and the information handling practices described herein.
In connection with your use of this Site, we may collect both personally identifiable information ("PII") and non-personally identifiable information ("Non-PII"). PII includes information such as your name, address, phone number, zip code, email address, and similar information. Non-PII may include, for example, your IP address, browser type, domain names, access dates, and similar information. (PII and Non-PII are collectively referred to as "Information.")
We may collect information from you through your voluntary submission to receive offers from the Site or access to certain resources on the Site. We also may collect information from your browser when you use the Site, using a variety of methods. The information collected by these automated methods may include, for example, your IP address, cookie information, a unique device or user ID, browser type, system type, the content and pages that you access on the Site, and the referring URL (the page from which you navigated to the Site). We may use cookies on the Site to recognize you and to store references to you and session validators on your device. We may use passively-collected information to administer, operate, and improve the Site and our other services, and to provide content tailored to you. We may combine Non-PII with PII.
If we directly combine any Non-PII with PII, we treat the combined information as PII under this Privacy Policy. Otherwise, we use information collected by passive means in aggregated or other non-personally identifiable forms.
We may use the information you provide for any purpose, including but not limited to: (1) providing materials you have requested; (2) contacting you regarding the potential purchase of insurance or other financial products; (3) personalizing our contact with you; (4) operating, providing, improving, and maintaining the Site; (5) developing new products and services; (6) preventing abusive and fraudulent use of the Site; and (7) sending administrative messages, content, and other features we believe may interest you, and for other administrative and internal business purposes permitted by law.
We may share your information with third parties who assist us in operating our business and servicing our clients. We may also disclose Information if, in good faith, we believe doing so is required by a subpoena or other judicial or administrative order, or otherwise required by law. We may disclose Information if we deem it appropriate or necessary to prevent violation of the Site's Terms of Use or our other agreements; take precautions against liability; protect our rights, property, or safety, or those of any individual or the general public; maintain the security and integrity of our services or infrastructure; protect ourselves from fraudulent, abusive, or unlawful uses; investigate and defend against third-party claims; or assist government enforcement agencies.
Your provision of information to us through the website will be considered a grant of permission for us to contact you through any means provided (including but not limited to mail, phone, text message, and fax). You have the right to opt out of further promotional contact from us. To be removed from an email mailing list, please send your request to contact@lonebeacon.com or to 2333 San Ramon Valley Blvd, Suite 200, San Ramon, CA 94583. It may take up to 10 days to process your request. This opt-out applies only to future promotional messages; we may still send administrative messages as permitted by law.
We maintain a variety of security measures to protect against the loss, misuse, and alteration of Information under our control. Although we make good faith efforts to maintain the security of such Information, we cannot guarantee that it will remain free from unauthorized access, use, disclosure, or alteration, and we cannot guarantee that our security measures will prevent unauthorized persons from accessing this information. We assume no liability to you or any other party in relation to the unauthorized access, use, or alteration of any information provided to us.
If we become aware of a security breach, we may attempt to notify you electronically so that you can take appropriate protective steps. By using the Site or providing Information to us, you agree that we may communicate with you electronically regarding security, privacy, and administrative issues relating to your use of the Site. If you believe there has been a breach of the Site's security, please contact us at (925) 314-8513.
We may update or amend this Privacy Policy at any time. No prior notice of any update or amendment is required, and all updates are effective upon being posted. We encourage you to periodically review this Privacy Policy. Your continued use of the Site constitutes your agreement to this Privacy Policy and any updates.
If you have questions about this Privacy Policy, you may contact us at (925) 314-8513.
All information available through this website is the property of Cadence Capital Investments (the "Company") or its Information Providers and is protected by copyright and intellectual property laws. All rights reserved.
You may not reproduce, retransmit, disseminate, sell, publish, or broadcast the information, nor use it in connection with creating, promoting, trading, or marketing financial instruments or products, without the express written consent of the Company or its licensors. You are entitled to use the information it contains for your private, non-commercial use only.
Cadence Capital Investments operates this website (the "website") to provide information, related features, and services (the "Service"). The terms and conditions set forth herein (the "Terms of Use") constitute a legally binding agreement between the Company and you regarding the terms on which the Company offers you access to the Service. By accessing and using this website, you agree to be bound by these Terms of Use and all applicable laws and regulations. If you do not agree, you are not authorized to access or use this website for any purpose.
The information provided on this website is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation, or which would subject the Company to any registration requirement within such jurisdiction or country. Neither the information nor any opinion contained in this website constitutes a solicitation or offer by the Company to buy or sell any securities, futures, options, or other financial instruments, or provide any investment advice or service.
The Company reserves the right to modify these Terms of Use at any time without giving you prior notice. Your use of the website following any such modification constitutes your agreement to follow and be bound by the Terms of Use as modified. We encourage you to review these Terms of Use whenever you use this website.
The Service, the website, and all data, information, and content that you see, hear, or otherwise experience on the website (the "Content") belong to the Company, its partners, affiliates, contributors, or third parties, and may be protected by U.S. and international copyright, trademark, intellectual property, and other laws. Content provided by third parties is used with their permission.
You may download, print, and store selected portions of the Content, provided that you (1) do not copy or post the Content on any network computer or transmit, distribute, publish, or broadcast the Content in any media, including a website; and (2) do not modify or alter the Content in any way, or delete or change any copyright or trademark notice. No right, title, or interest in any copied or downloaded Content is transferred to you. You may not use any of the marks appearing throughout this website without express written consent from the trademark owner, except as permitted by applicable law.
The information on this website is provided "as is." You expressly agree to assume total responsibility and risk for your use of the website and the Service. The Company makes no express or implied warranties, representations, or endorsements whatsoever with respect to the website or the Service, and expressly disclaims all warranties of any kind, express, implied, statutory, or otherwise, including implied warranties of merchantability, fitness for a particular purpose, title, and noninfringement. The Company does not warrant that the functions performed by the website or the Service will be uninterrupted, timely, secure, or error-free, or that defects will be corrected. The website, the Service, and the Content are provided on an "as is" and "as available" basis.
If you are dissatisfied with the website, any Content, or the Terms of Use, your sole and exclusive remedy is to discontinue using the website. Under no circumstances will the Company be liable for any damages whatsoever, including direct, incidental, consequential, exemplary, or indirect damages arising out of the use of or inability to use the website, the Service, or the Content. Because some states do not allow the exclusion or limitation of liability for consequential or incidental damages, some of the above limitations may not apply to you.
For details on how we handle personal information, please see our Privacy Policy.
You agree not to take any action that interferes with the proper working of the website; imposes an unreasonable or disproportionately large load on the website's infrastructure; might compromise the security of the website; renders the website or the Service inaccessible to others; or otherwise causes damage to the website or any Content. You agree not to add to, subtract from, or otherwise modify the Content except as expressly authorized by the Company in these Terms of Use or by a written agreement between you and the Company.
Entire agreement. These Terms of Use constitute the entire agreement of the parties with respect to the subject matter hereof and supersede all previous written or oral agreements. No waiver by the Company of any breach or default shall be deemed a waiver of any preceding or subsequent breach or default.
Correction of errors and inaccuracies. The information on the website may contain typographical or other errors or inaccuracies and may not be complete or current. We reserve the right to correct any errors, inaccuracies, or omissions and to change or update information at any time without prior notice. We do not, however, guarantee that any errors will be corrected.
No endorsements of links. Hypertext links to third-party websites or information do not constitute or imply an endorsement, sponsorship, or recommendation by the Company. You acknowledge that the Company is not responsible for the availability of any such websites and does not endorse or warrant, and is not responsible or liable for, any such website or its content. Links to other sites are provided for convenience only.
Enforcement. If any part of these Terms of Use is determined to be invalid or unenforceable, it will not impact any other provision, all of which will remain in full force and effect. These Terms of Use are governed by, and will be interpreted in accordance with, the laws of the State of California, without regard to conflict of laws provisions. You consent to the exclusive jurisdiction and venue of courts in California, U.S.A., regarding any disputes relating to these Terms of Use, the Company's Privacy Statement, your use of the website, the Service, or Content contained therein.
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. Please consult legal or tax professionals for specific information regarding your individual situation. The opinions expressed and material provided are for general information and should not be considered a solicitation for the purchase or sale of any security.
Cadence Capital Investments is not affiliated with, endorsed by, or sponsored by Chevron Corporation, AT&T Inc., or Toyota Motor North America, Inc. Company names and benefit plan names, including the Chevron Employee Savings Investment Plan, the Chevron Retirement Plan, the AT&T Pension Benefit Plan, the AT&T Retirement Savings Plan, the AT&T Savings and Security Plan, the Toyota Motor North America, Inc. Retirement Savings Plan, and the Toyota Motor Sales, U.S.A., Inc. Pension Plan, are trademarks or plan names of their respective owners and are used on this site for identification and educational purposes only. Benefit plan provisions and IRS limits change and vary by individual circumstance; confirm current details with your employer's plan documents and plan administrator before acting.
We take protecting your data and privacy very seriously. As of January 1, 2020, the California Consumer Privacy Act (CCPA) suggests the following link as an extra measure to safeguard your data: Do not sell my personal information.