Employer benefits
What is Net Unrealized Appreciation
September 1, 2026
By Jamie Hargrave, Cadence Capital Investments
What is Net Unrealized Appreciation
Employer benefits
Learn what is net unrealized appreciation and how this tax rule for company stock can impact your retirement. See how growth may be taxed at capital gains ra...
A rising interest rate environment is often viewed as a positive sign for savers, yet for a Chevron professional, it can actually lead to a smaller pension lump sum. Deciding between a monthly annuity and a single lump sum depends on how the benefit coordinates with your other income, and the election is generally irreversible once payment begins.
This article describes how the Chevron Retirement Plan works in general terms, how interest rates affect a lump sum calculation, and how the pension decision interacts with the savings plan. It is educational and is not tax or legal advice. Consult your CPA or attorney about your specific situation.
Cadence Capital Investments is an independent firm and is not affiliated with, endorsed by, or sponsored by Chevron Corporation.
Plan terms govern. Vesting schedules, benefit formulas, eligibility, election windows, and available payment forms are set by the plan and can be amended. Every plan description below is general and drawn from publicly available information. Confirm what applies to you through your summary plan description, your benefit statements, and the Chevron Human Resources Service Center before making any election.
• The Chevron Retirement Plan is a defined benefit pension: the benefit is determined by a formula rather than by contributions and market results.
• The choice between a monthly payment and a lump sum is generally irreversible once payment begins.
• A lump sum is a present value calculation, so its size moves inversely with the interest rates the plan uses.
• The pension election interacts with savings plan decisions, Social Security timing, and the tax year everything lands in.
• Cadence Capital Investments is fee-based, not fee-only, because an affiliate may earn commissions on certain insurance and annuity products.
• How a defined benefit pension works
• Monthly payments compared with a lump sum
• How interest rates affect the calculation
• Tax and distribution rules
• Coordinating the pension with the savings plan
• Frequently asked questions
The Chevron Retirement Plan is a defined benefit plan. The employer funds it, and the benefit is determined by a formula rather than by an account balance that rises and falls with markets. That is the structural difference from the savings plan, where you contribute, you select investments, and the balance depends on both.
Defined benefit formulas generally combine years of service with a measure of pay, often an average of your highest consecutive earning period. The specific formula, the averaging period, and any offsets are set by the plan document and can be amended by the plan sponsor.
Request a current benefit projection rather than estimating from a formula description. The projection is the number the election gets modeled against.
Vesting is the point at which your right to a benefit becomes non-forfeitable. ERISA sets minimum vesting standards that qualified pension plans must meet, and individual plans may be more generous than the minimum. The schedule that applies to you, along with plan entry rules, is stated in your summary plan description.
Where a departure date falls close to a vesting or eligibility threshold, confirming the exact terms before setting the date is worth doing. This is one of the few places in a retirement transition where a few weeks can matter materially.
The plan generally permits an election between a series of monthly payments and a single lump sum. Once payment begins, the election generally cannot be changed, regardless of how circumstances or the economic environment shift afterward.
There is no universally correct answer. The comparison moves with the interest rates in effect at the election, your other income sources, your tax situation, your health, and your spouse's needs.
A lump sum is the present value of the future monthly payments, paid as a single amount that can generally be rolled to an IRA or taken as cash.
It gives you control over the timing of withdrawals and leaves whatever remains to pass by beneficiary designation. It also transfers investment risk and longevity risk to you: the money has to be managed so that it supports spending across an unknown number of years. That is a real responsibility rather than a footnote, and how comfortably you would carry it through a difficult market is a legitimate input to the decision.
A monthly payment form produces an amount determined by the plan's formula and your election, paid on the plan's schedule for as long as the elected form provides.
These payments come from the pension plan, not from an insurance contract. Benefits under a qualified defined benefit plan are funded by the plan and, within statutory limits, guaranteed by the Pension Benefit Guaranty Corporation. That is a different backing arrangement from an annuity purchased from an insurance company, where payments depend on the claims-paying ability of the issuing insurer. Where a plan settles its obligations by purchasing annuity contracts from an insurer, the backing changes; that is worth asking about specifically.
Payment forms typically include a single life option and joint and survivor options. A single life form pays for your life only. A joint and survivor form pays a reduced amount while you are living and continues a benefit to a designated survivor afterward. Spousal consent requirements may apply to certain elections.
The comparison that matters is not which form pays more on paper. It is what each household member would be living on under each scenario, at each stage of a long retirement.
A lump sum is a present value: it converts a stream of future payments into one amount today. The rates used in that conversion are specified by the plan and reset periodically, and the relationship is inverse. When those rates rise, the calculated lump sum for the same underlying benefit generally decreases. When they fall, it generally increases.
Qualified plans use interest rate assumptions published for this purpose, commonly referred to as segment rates, along with prescribed mortality assumptions. The rates are published periodically and are available through IRS.gov.
Because the calculation uses these figures, the same benefit can produce a different lump sum depending on when the election is made. That is arithmetic rather than a market call.
Plans specify which period's rates apply to a given commencement date, generally through a stated lookback provision. The practical consequence is that the rate applied to your election may have been set some months earlier, and that different commencement dates can fall under different rate sets.
Finding out your plan's lookback provision and reset schedule early is worth doing, because it determines when the comparison is worth running and how much lead time a change in commencement date requires. This is preparation, not prediction; nothing here is a forecast of interest rates.
Pension distributions are generally taxed as ordinary income in the year received. This is educational and is not tax advice; consult your CPA or attorney before any distribution election.
Where you separate from service with an employer in or after the calendar year you turn 55, distributions from that employer's qualified plan may avoid the additional 10 percent early distribution tax. Ordinary income tax still applies.
The relief attaches to the plan of the employer you separated from. It does not apply to IRAs or to plans of previous employers. Rolling assets into an IRA generally closes the window for those assets, after which the standard age 59 and a half rules apply.
A direct rollover is a trustee-to-trustee transfer from the plan to an IRA or another qualified plan. It generally avoids mandatory withholding and defers tax until later distributions.
An indirect rollover occurs when the distribution is paid to you first. Two things follow. Eligible rollover distributions paid directly to you are generally subject to mandatory 20 percent federal income tax withholding, so only 80 percent arrives. You then have 60 days to deposit the funds into another qualified plan or IRA, and to complete a full rollover you must replace the withheld 20 percent from other funds. Missing the 60-day window generally makes the distribution taxable, and the additional 10 percent tax may apply if you are under 59 and a half and no exception is available.
The direct route avoids both traps, which is why it is the default recommendation in most circumstances.
The pension and the savings plan are separate benefits with separate rules, and they eventually have to merge into one income picture.
Reviewed together, the questions become which source funds which period, what the tax picture looks like in the year the pension election takes effect, and how savings plan distributions should be sized around it. A large distribution in a year that also includes the start of pension payments can move income into a higher bracket, so the timing is worth modeling rather than discovering afterward.
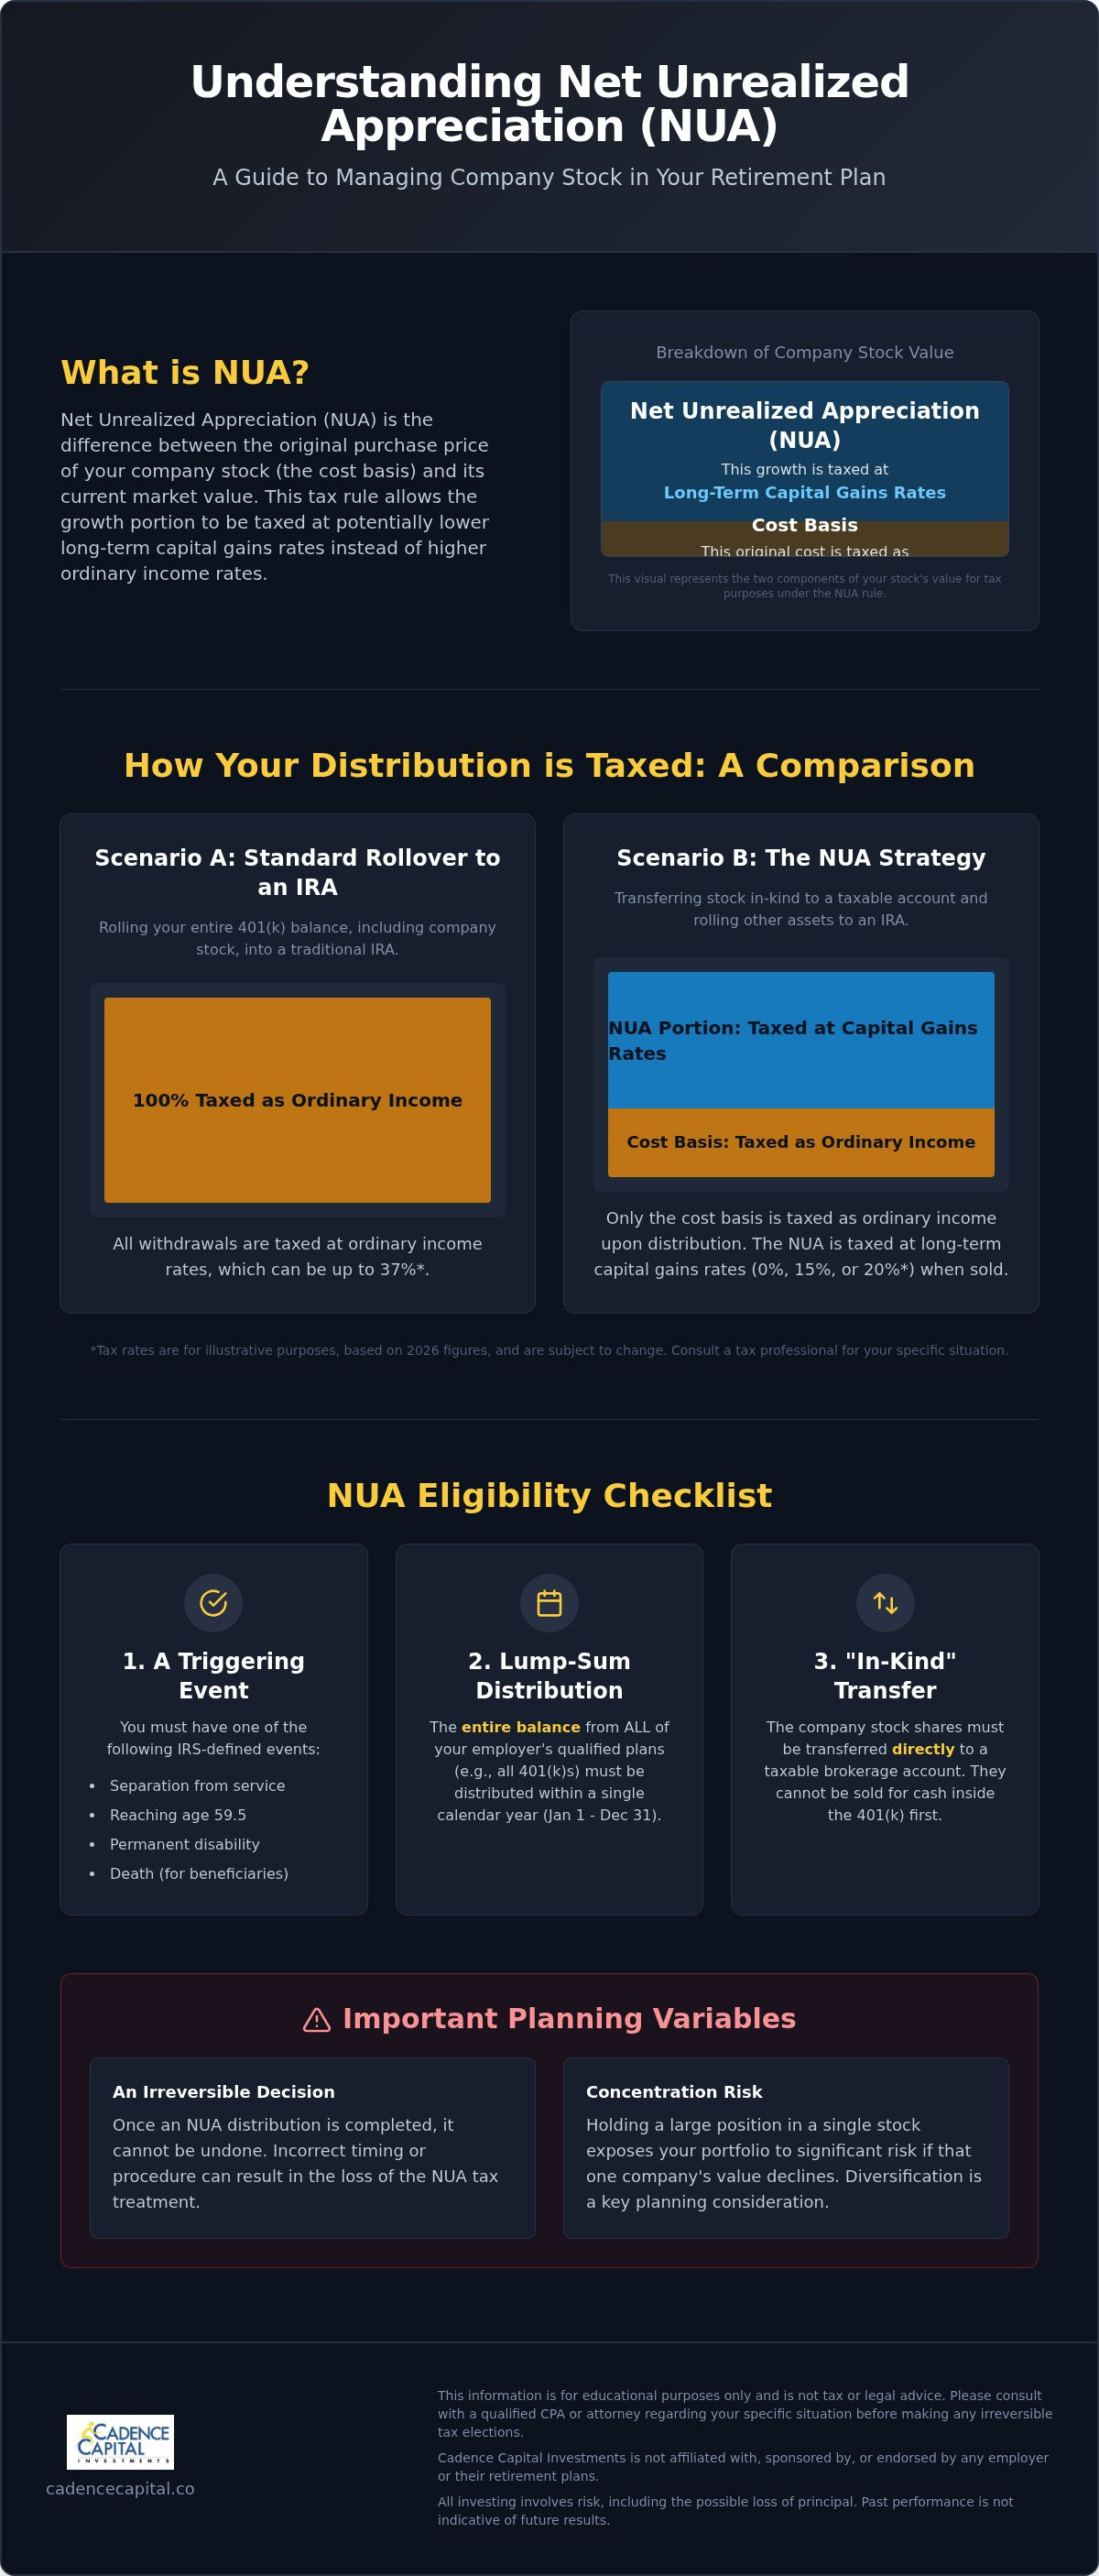
Where appreciated company stock sits inside the savings plan, a Net Unrealized Appreciation election may also be relevant, and it has its own strict conditions and its own irreversibility. It is worth evaluating alongside the pension decision rather than after it, since both can land in the same tax year.
Investment advisory services at Cadence Capital Investments are offered through Prosperity Financial, a Registered Investment Advisor, which acts in a fiduciary capacity with respect to the advisory services it provides. Securities are offered through Fortune Financial Services, LLC, a Registered Broker/Dealer and member FINRA and SIPC; brokerage recommendations are subject to Regulation Best Interest. Insurance and annuity products are offered through licensed affiliates and agents, which means the firm is fee-based rather than fee-only.
Because an affiliate may earn commissions on certain products, a conflict of interest exists. We manage it by disclosing the compensation applicable to any recommendation before it is made and by describing the full structure in our Form CRS. Jamie Hargrave works directly with families in San Ramon on these transitions, and we meet quarterly to review the plan and adjust as circumstances change.
Because the pension election cannot be undone, we encourage a second opinion and a family conversation before the paperwork is submitted.
Generally by a formula combining years of service with a measure of pay, often an average of your highest consecutive earning period. The employer funds the plan and carries the investment risk for the benefit. The specific formula and averaging period are set by the plan document and can be amended, so request a current benefit projection from the plan administrator rather than estimating.
Where you separate from service with an employer in or after the calendar year you turn 55, distributions from that employer's qualified plan may avoid the additional 10 percent early distribution tax. Ordinary income tax still applies. It does not extend to IRAs or to plans of previous employers. These provisions are set by statute and subject to change; consult your CPA.
A direct trustee-to-trustee rollover of an eligible lump sum to a traditional IRA is generally not taxable at the time of transfer, with tax deferred until later distributions. An indirect rollover is treated differently and is generally subject to mandatory 20 percent withholding and a 60-day deadline. This is educational information rather than tax advice; consult a tax professional before initiating any transfer.
It depends on your income needs, your other sources, and the rate environment applied to your calculation, since a lump sum value moves inversely with the rates the plan uses. Commencement date also interacts with Social Security timing and with any savings plan distributions in the same tax year. The useful step is modeling several commencement dates against your actual projection before an election window closes.
Generally no. The election is treated as a one-time choice and is not designed to be revisited once payment begins, which is why the modeling belongs before the paperwork rather than after. Confirm the specific rules applying to your benefit with your plan administrator, since provisions differ and can change.
No. Cadence Capital Investments is not affiliated with, endorsed by, or sponsored by Chevron Corporation, and nothing here should be read as an employer-approved benefits resource. We provide independent retirement planning for employees and retirees seeking an outside perspective. Investment advisory services are offered through Prosperity Financial, a Registered Investment Advisor, and the firm is fee-based rather than fee-only.
This article is for general informational and educational purposes only. It is not individualized investment, tax, or legal advice, is not a recommendation to buy, sell, or hold any security or insurance product, and does not account for your specific circumstances. Consult your CPA or attorney regarding your individual tax and legal situation. Investing involves risk, including the possible loss of principal. Past performance is not indicative of future results.
Tax rules, interest rate assumptions, and age triggers are stated as of the publication date and are subject to legislative and regulatory change; IRS.gov publishes current figures. Descriptions of employer benefit plans are general, are drawn from publicly available information as of the publication date, and are subject to amendment by the plan sponsor. Confirm all plan provisions, including vesting, formula, eligibility, and available payment forms, with your plan administrator, your summary plan description, and your employer's human resources service center before making any election.
Advisory services offered through Prosperity Financial, a Registered Investment Advisor. Securities offered through Fortune Financial Services, LLC, a Registered Broker/Dealer, member FINRA / SIPC. Insurance and annuity products are offered through licensed affiliates and agents; product guarantees are subject to the claims-paying ability of the issuing company. Because an affiliate may earn commissions on certain products, Cadence Capital Investments is fee-based rather than fee-only.
Cadence Capital Investments is not affiliated with, endorsed by, or sponsored by Chevron Corporation or any other employer, plan sponsor, plan administrator, or government agency named in this article. All company, plan, and product names are the property of their respective owners and are used for identification purposes only. Nothing in this article is a comparison to, or an assessment of, any other advisory firm.
We value your privacy, and we want to help make your experience with Cadence Capital Investments as satisfying and safe as possible. We have established this Privacy Policy to explain how we receive, use, and share information you may provide in connection with your access to this website.
The Site is intended for use only by individuals over the age of 18 who are accessing the Site from inside the United States. By using the Site or submitting any information to us, you acknowledge that you are over the age of 18, are in the United States, and that you consent to our use and sharing of information collected or submitted as described in this Privacy Policy. This Privacy Policy is incorporated into and is subject to the Site's Terms of Use. By using the Site, you expressly consent to the terms of this Privacy Policy and the information handling practices described herein.
In connection with your use of this Site, we may collect both personally identifiable information ("PII") and non-personally identifiable information ("Non-PII"). PII includes information such as your name, address, phone number, zip code, email address, and similar information. Non-PII may include, for example, your IP address, browser type, domain names, access dates, and similar information. (PII and Non-PII are collectively referred to as "Information.")
We may collect information from you through your voluntary submission to receive offers from the Site or access to certain resources on the Site. We also may collect information from your browser when you use the Site, using a variety of methods. The information collected by these automated methods may include, for example, your IP address, cookie information, a unique device or user ID, browser type, system type, the content and pages that you access on the Site, and the referring URL (the page from which you navigated to the Site). We may use cookies on the Site to recognize you and to store references to you and session validators on your device. We may use passively-collected information to administer, operate, and improve the Site and our other services, and to provide content tailored to you. We may combine Non-PII with PII.
If we directly combine any Non-PII with PII, we treat the combined information as PII under this Privacy Policy. Otherwise, we use information collected by passive means in aggregated or other non-personally identifiable forms.
We may use the information you provide for any purpose, including but not limited to: (1) providing materials you have requested; (2) contacting you regarding the potential purchase of insurance or other financial products; (3) personalizing our contact with you; (4) operating, providing, improving, and maintaining the Site; (5) developing new products and services; (6) preventing abusive and fraudulent use of the Site; and (7) sending administrative messages, content, and other features we believe may interest you, and for other administrative and internal business purposes permitted by law.
We may share your information with third parties who assist us in operating our business and servicing our clients. We may also disclose Information if, in good faith, we believe doing so is required by a subpoena or other judicial or administrative order, or otherwise required by law. We may disclose Information if we deem it appropriate or necessary to prevent violation of the Site's Terms of Use or our other agreements; take precautions against liability; protect our rights, property, or safety, or those of any individual or the general public; maintain the security and integrity of our services or infrastructure; protect ourselves from fraudulent, abusive, or unlawful uses; investigate and defend against third-party claims; or assist government enforcement agencies.
Your provision of information to us through the website will be considered a grant of permission for us to contact you through any means provided (including but not limited to mail, phone, text message, and fax). You have the right to opt out of further promotional contact from us. To be removed from an email mailing list, please send your request to contact@lonebeacon.com or to 2333 San Ramon Valley Blvd, Suite 200, San Ramon, CA 94583. It may take up to 10 days to process your request. This opt-out applies only to future promotional messages; we may still send administrative messages as permitted by law.
We maintain a variety of security measures to protect against the loss, misuse, and alteration of Information under our control. Although we make good faith efforts to maintain the security of such Information, we cannot guarantee that it will remain free from unauthorized access, use, disclosure, or alteration, and we cannot guarantee that our security measures will prevent unauthorized persons from accessing this information. We assume no liability to you or any other party in relation to the unauthorized access, use, or alteration of any information provided to us.
If we become aware of a security breach, we may attempt to notify you electronically so that you can take appropriate protective steps. By using the Site or providing Information to us, you agree that we may communicate with you electronically regarding security, privacy, and administrative issues relating to your use of the Site. If you believe there has been a breach of the Site's security, please contact us at (925) 314-8513.
We may update or amend this Privacy Policy at any time. No prior notice of any update or amendment is required, and all updates are effective upon being posted. We encourage you to periodically review this Privacy Policy. Your continued use of the Site constitutes your agreement to this Privacy Policy and any updates.
If you have questions about this Privacy Policy, you may contact us at (925) 314-8513.
All information available through this website is the property of Cadence Capital Investments (the "Company") or its Information Providers and is protected by copyright and intellectual property laws. All rights reserved.
You may not reproduce, retransmit, disseminate, sell, publish, or broadcast the information, nor use it in connection with creating, promoting, trading, or marketing financial instruments or products, without the express written consent of the Company or its licensors. You are entitled to use the information it contains for your private, non-commercial use only.
Cadence Capital Investments operates this website (the "website") to provide information, related features, and services (the "Service"). The terms and conditions set forth herein (the "Terms of Use") constitute a legally binding agreement between the Company and you regarding the terms on which the Company offers you access to the Service. By accessing and using this website, you agree to be bound by these Terms of Use and all applicable laws and regulations. If you do not agree, you are not authorized to access or use this website for any purpose.
The information provided on this website is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation, or which would subject the Company to any registration requirement within such jurisdiction or country. Neither the information nor any opinion contained in this website constitutes a solicitation or offer by the Company to buy or sell any securities, futures, options, or other financial instruments, or provide any investment advice or service.
The Company reserves the right to modify these Terms of Use at any time without giving you prior notice. Your use of the website following any such modification constitutes your agreement to follow and be bound by the Terms of Use as modified. We encourage you to review these Terms of Use whenever you use this website.
The Service, the website, and all data, information, and content that you see, hear, or otherwise experience on the website (the "Content") belong to the Company, its partners, affiliates, contributors, or third parties, and may be protected by U.S. and international copyright, trademark, intellectual property, and other laws. Content provided by third parties is used with their permission.
You may download, print, and store selected portions of the Content, provided that you (1) do not copy or post the Content on any network computer or transmit, distribute, publish, or broadcast the Content in any media, including a website; and (2) do not modify or alter the Content in any way, or delete or change any copyright or trademark notice. No right, title, or interest in any copied or downloaded Content is transferred to you. You may not use any of the marks appearing throughout this website without express written consent from the trademark owner, except as permitted by applicable law.
The information on this website is provided "as is." You expressly agree to assume total responsibility and risk for your use of the website and the Service. The Company makes no express or implied warranties, representations, or endorsements whatsoever with respect to the website or the Service, and expressly disclaims all warranties of any kind, express, implied, statutory, or otherwise, including implied warranties of merchantability, fitness for a particular purpose, title, and noninfringement. The Company does not warrant that the functions performed by the website or the Service will be uninterrupted, timely, secure, or error-free, or that defects will be corrected. The website, the Service, and the Content are provided on an "as is" and "as available" basis.
If you are dissatisfied with the website, any Content, or the Terms of Use, your sole and exclusive remedy is to discontinue using the website. Under no circumstances will the Company be liable for any damages whatsoever, including direct, incidental, consequential, exemplary, or indirect damages arising out of the use of or inability to use the website, the Service, or the Content. Because some states do not allow the exclusion or limitation of liability for consequential or incidental damages, some of the above limitations may not apply to you.
For details on how we handle personal information, please see our Privacy Policy.
You agree not to take any action that interferes with the proper working of the website; imposes an unreasonable or disproportionately large load on the website's infrastructure; might compromise the security of the website; renders the website or the Service inaccessible to others; or otherwise causes damage to the website or any Content. You agree not to add to, subtract from, or otherwise modify the Content except as expressly authorized by the Company in these Terms of Use or by a written agreement between you and the Company.
Entire agreement. These Terms of Use constitute the entire agreement of the parties with respect to the subject matter hereof and supersede all previous written or oral agreements. No waiver by the Company of any breach or default shall be deemed a waiver of any preceding or subsequent breach or default.
Correction of errors and inaccuracies. The information on the website may contain typographical or other errors or inaccuracies and may not be complete or current. We reserve the right to correct any errors, inaccuracies, or omissions and to change or update information at any time without prior notice. We do not, however, guarantee that any errors will be corrected.
No endorsements of links. Hypertext links to third-party websites or information do not constitute or imply an endorsement, sponsorship, or recommendation by the Company. You acknowledge that the Company is not responsible for the availability of any such websites and does not endorse or warrant, and is not responsible or liable for, any such website or its content. Links to other sites are provided for convenience only.
Enforcement. If any part of these Terms of Use is determined to be invalid or unenforceable, it will not impact any other provision, all of which will remain in full force and effect. These Terms of Use are governed by, and will be interpreted in accordance with, the laws of the State of California, without regard to conflict of laws provisions. You consent to the exclusive jurisdiction and venue of courts in California, U.S.A., regarding any disputes relating to these Terms of Use, the Company's Privacy Statement, your use of the website, the Service, or Content contained therein.
The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. Please consult legal or tax professionals for specific information regarding your individual situation. The opinions expressed and material provided are for general information and should not be considered a solicitation for the purchase or sale of any security.
Cadence Capital Investments is not affiliated with, endorsed by, or sponsored by Chevron Corporation, AT&T Inc., or Toyota Motor North America, Inc. Company names and benefit plan names, including the Chevron Employee Savings Investment Plan, the Chevron Retirement Plan, the AT&T Pension Benefit Plan, the AT&T Retirement Savings Plan, the AT&T Savings and Security Plan, the Toyota Motor North America, Inc. Retirement Savings Plan, and the Toyota Motor Sales, U.S.A., Inc. Pension Plan, are trademarks or plan names of their respective owners and are used on this site for identification and educational purposes only. Benefit plan provisions and IRS limits change and vary by individual circumstance; confirm current details with your employer's plan documents and plan administrator before acting.
We take protecting your data and privacy very seriously. As of January 1, 2020, the California Consumer Privacy Act (CCPA) suggests the following link as an extra measure to safeguard your data: Do not sell my personal information.